Pet groomer insurance for Pennsylvania salons and mobile operators
Pet groomer insurance in Pennsylvania for brick-and-mortar salons and mobile groomers, including general liability, animal bailee, professional liability, commercial auto, and equipment — shopped across 10+ carriers by a local independent agent.
Built for the table, the tub, and the van
Whether you work in a storefront salon or pull a van into a client’s driveway, we build pet groomer insurance in Pennsylvania around the way you actually work.
Salon or mobile: pet groomer insurance in Pennsylvania that fits how you work
The risks are related, but they are not the same. Therefore, pet groomer insurance in Pennsylvania should reflect whether you work in a shop, on the road, or both.
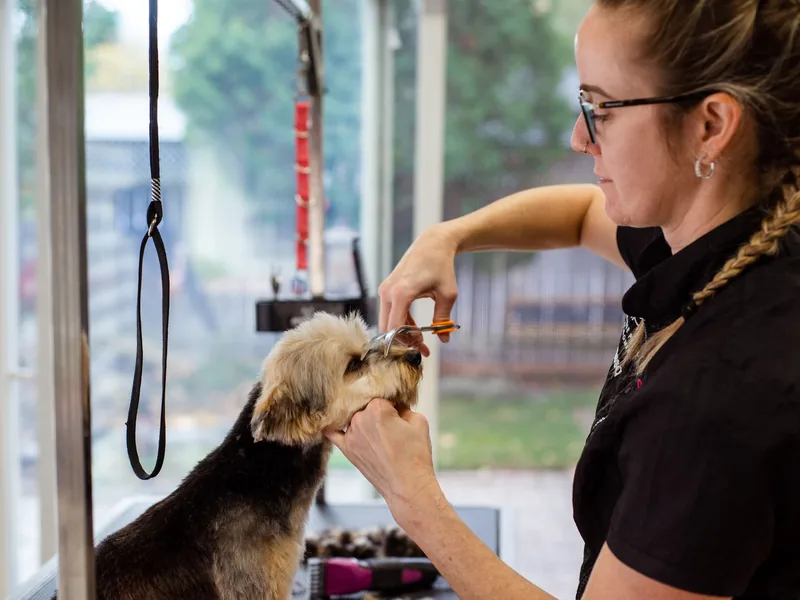
- The shop itself: wet floors, a waiting area, and customers in the lobby create premises liability that a mobile route does not.
- Tables, tubs, and buildout: hydraulic tables, high-velocity dryers, and tenant improvements usually belong on a BOP or property form, not on general liability.
- Boarding or daycare: more animals in your care at once can change both coverage and Pennsylvania kennel licensing.
- Landlord certificates: most landlords ask you to name them as an additional insured. Send us the wording and we will review it with the policy.
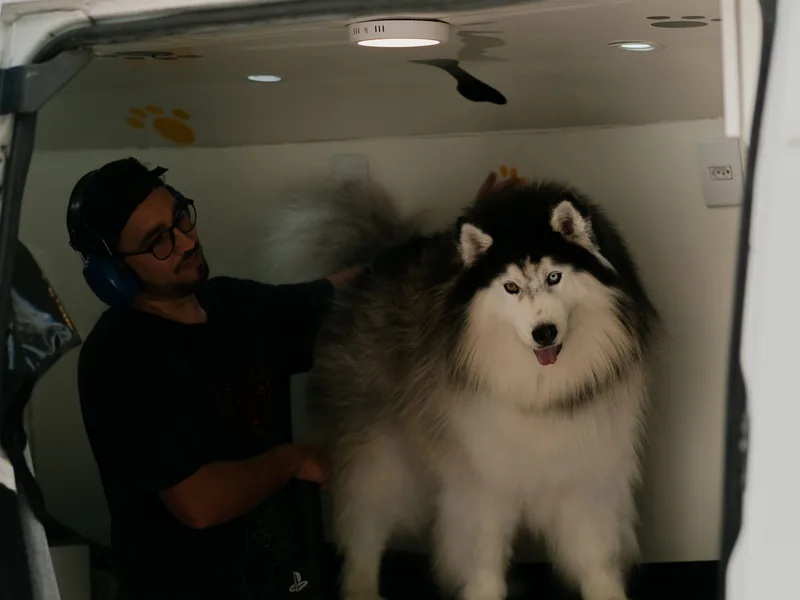
- The van is the business: a converted grooming van generally needs commercial auto, not a personal auto policy.
- Conversion equipment: tubs, plumbing, water tanks, and generators often need inland marine or scheduled equipment coverage in addition to the vehicle.
- Work at the client’s home: confirm that liability and animal bailee apply while you park and groom off your own premises.
- Overnight parking and radius: where the van sits at night, and how far you drive, affect theft and auto exposure.
Coverage that protects the pets in your care
A standard general liability policy often excludes animals in your care, custody, or control. As a result, most shops add animal bailee when they shop pet groomer insurance in Pennsylvania, along with the lines below.
The coverage designed for injury, illness, death, escape, or loss of a pet while it is in your care, subject to the policy terms and per-animal limits. A typical general-liability form generally does not cover the animal itself.
Third-party injury and property damage from your operations — for example a client who slips near the tub, or a visitor bitten in the lobby — subject to the form and any endorsements. Landlords and venues often require it.
Helps respond if a client claims your grooming itself caused harm — a bad clip, a reaction to a shampoo or dip, or a handling decision. This is separate from animal bailee, and the two often work together.
Mobile grooming vans and other vehicles used for the business, plus hired & non-owned auto when someone runs errands in a personal car. A converted van usually does not belong on a personal auto policy.
More Pennsylvania pet groomer insurance options
Clippers, dryers, tubs, and tables — in the salon, in the van, or in transit. Conversion equipment such as generators and water tanks often goes on this coverage when the auto policy does not fully cover it.
Your salon, if you have one — building (if owned), contents, tenant improvements, and often business income — packaged with general liability when a BOP is a good fit.
Medical bills and lost wages if a dog bites or scratches an employee, or someone gets hurt lifting a dog. Because Pennsylvania requires workers’ compensation for most employers with even one employee, part-time bathers count too. For state rules, see the Pennsylvania Department of Labor & Industry workers’ compensation page.
Extra liability limits above your general liability, auto, and employer’s liability. Some landlords and commercial clients ask for this on the certificate.
Help responding if client records, online booking, or payments are hit by a phishing email, ransomware, or a compromised account.
Pennsylvania licensing: the state does not issue a statewide pet groomer license. However, grooming services are generally subject to sales tax, and the PA Business One-Stop animal groomers guide is a good starting point for registration. Local business or zoning rules can still apply.
In addition, if you offer boarding or daycare, a kennel license from the Bureau of Dog Law Enforcement may apply. A shop that only grooms or trains generally falls under different rules than a boarding kennel, but the facts of your operation matter.
After the dog is on the table
Nicks, dryer injuries, and escapes are the questions groomers raise most often. It is worth understanding which policy might respond before a client calls, and we will not promise that a policy covers a given claim.
- Nicks, cuts, and clipper burns: these usually involve the pet in your care, so animal bailee is the line that typically responds to them, subject to the terms and per-animal limits. General liability generally does not cover the animal itself.
- Heat stroke and dryer injuries: unattended or overheated dryers can produce some of the more serious grooming claims. Therefore, it is worth comparing your bailee limit with the cost of emergency veterinary care.
- Escapes: a dog that slips a loop at handoff, or darts from a van door, can lead to a lost-pet claim and, in some cases, injury to a passerby. Bailee and general liability may each have a role, depending on the facts.
- Bites and slip-and-falls: a bite to your employee is generally a workers’ compensation matter. Meanwhile, a bite or a fall that hurts a customer is typically a general-liability question.
Why LWG for pet groomer insurance in Pennsylvania
In fact, Looker Wolfe & Gephart has been helping Pennsylvania businesses since 1987, including shops and mobile operators who need pet groomer insurance. If you also want a broader business package, start from our commercial insurance page.
- We shop 10+ carriers: As an independent agency, we therefore compare multiple markets, not just one company’s products.
- Pennsylvania only: We write exclusively in PA, so we know the state’s workers’ comp system and the difference between a grooming-only shop and a kennel.
- Local brick-and-mortar: You get real people at 44 Oak Park Rd, Harrisburg, rather than an online lead-gen site that sells your info.
- Call or text: Reach us at 717-657-9944, Monday–Friday 8–5, so you get the same local team every time.
- Salon and mobile: We quote storefront shops, converted vans, and operators who do both, including equipment and auto.
- Certificates fast: If a landlord or a commercial client needs you additional insured, text or email the contract wording.
Pennsylvania pet groomer insurance FAQ
Does general liability cover a pet injured during a groom?
Usually not, at least not on a typical commercial general-liability form. Those forms generally exclude damage to property in your care, custody, or control, and a pet in your hands or on your table counts as property for that purpose. Animal bailee coverage — sometimes called pet protection or care-custody-control — is the line designed for injury, illness, death, escape, or loss of an animal in your care, subject to the policy terms and per-animal limits. We will not promise that a policy covers a given claim.
What is animal bailee coverage?
It is the coverage that may respond when a pet in your care is hurt, becomes ill, dies, is lost, or escapes, subject to the form. Carriers often write limits per animal and in the aggregate, and they vary by carrier. Compare the limit with the cost of emergency veterinary care. Animal bailee is not the same as professional liability, and a well-built pet groomer insurance package in Pennsylvania often includes both.
What is the difference between animal bailee and professional liability?
Animal bailee is aimed at physical injury or loss of the pet in your care. Professional liability is aimed at a claim that your professional service itself fell short — for example a clip the client disputes, a reaction to a product you used, or a handling decision. Some pet-care packages combine the two, but they answer different questions. We will review both with you.
Pets in your care, and the grooming van
I run a mobile grooming van. What extra coverage do I need?
In addition to general liability, animal bailee, and professional liability, a mobile groomer typically needs commercial auto for the van. Built-in tubs, plumbing, water tanks, and generators often go on inland marine or scheduled equipment coverage, because a basic auto policy may not fully cover conversion equipment. Also confirm that liability and bailee apply while you work at a client’s property, and tell us where the van parks overnight.
Will my personal auto policy or homeowners insurance cover the van or the shop?
Typically no. A personal auto policy often excludes a vehicle used primarily for business, especially a converted grooming van. Likewise, a homeowners insurance policy generally will not take the place of a commercial auto policy, a business owner’s policy, or animal bailee coverage. If you groom from a home-based salon, we will still look at the business exposures separately from your personal lines.
Licensing and workers’ comp
Do I need a Pennsylvania groomer license?
Pennsylvania does not issue a statewide pet groomer license. You typically still need ordinary business registration, and grooming services are generally subject to sales tax — the PA Business One-Stop animal groomers guide is the official starting point. Local zoning or business rules can also apply. If you offer boarding or daycare, a kennel license may apply; the rules generally differ for a shop that only grooms, but the facts of your operation matter.
Do I need workers’ compensation in Pennsylvania if I only have one bather?
Generally, yes. Pennsylvania requires most employers to carry workers’ compensation if they have even one employee who could get hurt on the job in this state — including part-time bathers and, in many cases, family members who work in the business. Sole proprietors and certain partners or executive officers may be able to exclude themselves. Bites, scratches, and lifting injuries are common in this trade. We’ll walk through how you run your shop, and you can also start from our workers’ compensation quote page.
Contractors, boarding, and what you need to quote
What about independent contractor groomers or booth rental?
You should collect current certificates showing general liability and workers’ compensation (when they have employees) before someone grooms under your roof or brand. If you treat a person as an independent contractor but does not carry coverage, their injuries or their mistakes can still come back to the shop, and an auditor may add their payroll at a workers’ comp audit. Tell us how you handle booth rental so we can shop it accurately.
We also offer daycare or boarding. Does that change the quote?
It can. More animals in your care at one time can affect animal bailee limits, and Pennsylvania kennel licensing may apply when you board or offer daycare. Tell us on the form, even if boarding is only an add-on to the grooming shop. We will then match the submission to markets that write that mix.
What do I need to get a quote?
A description of whether you are a salon, a mobile groomer, or both; the services you offer; about how many animals you groom per week; receipts and payroll; employee and contractor information; salon size or van year, make, model, and equipment values; and your current carrier, expiration date, and any claims in the last five years. Finally, the form below walks you through it — estimates are fine.
Get your Pennsylvania pet groomer insurance quote
A few short steps to request pet groomer insurance in Pennsylvania. However, if you don’t know an exact number, a good estimate is fine — we’ll confirm details with you. If you need a quote for another type of business, start from our commercial quotes page.
Please Note: We offer insurance coverage in Pennsylvania only. Therefore, the form below is for pet groomer insurance in Pennsylvania, including salons and mobile groomers.